Should you accept VA and FHA offers when selling your Lake Balboa home, and what do you need to know before you do?
Yes. Accepting VA and FHA buyers in Lake Balboa expands your buyer pool significantly, and with the 2026 loan limit at $1,249,125, most homes here qualify. A few simple prep steps keep closings on track.
Why Lake Balboa Sellers Should Pay Attention to This Right Now
If you’re selling a home in Lake Balboa in 2026, the buyer pool you attract directly impacts your final sale price, your days on market, and your negotiating leverage. Excluding VA and FHA buyers means turning away a meaningful chunk of qualified purchasers, many of whom are ready, pre-approved, and motivated.
Here’s what makes this especially relevant right now: Lake Balboa single-family homes had a median list price of $950,000 as of May/June 2026, per local MLS data, and a sold-to-list ratio of 104.6%. That means sellers are getting above asking price in this neighborhood. But the inventory supply sits at just 2.18 months, which means every additional qualified buyer who walks through your door creates more competition for your property. With only 14 closed single-family sales in the most recent reporting period (per CRMLS, April 2026), you cannot afford to limit your audience.
I’m a U.S. Army veteran, and I purchased my own home using a VA loan. I was as strong a buyer as anyone, even with zero down payment. What I tell my sellers is this: the financing source does not determine the strength of the offer. The buyer’s qualification does.
Understanding the 2026 VA and FHA Loan Limits for Lake Balboa
So what are the actual numbers? The 2026 FHA loan limit for a single-family home in Los Angeles County is $1,249,125, according to Community First Mortgage. The 2026 VA loan limit matches at $1,249,125, per Homebuyer.com data.
Now compare that to Lake Balboa’s pricing. Single-family homes here generally trade in the $850,000 to $1.2 million range, with the median estimated value sitting at $904,210 as of May/June 2026 (per local market reporting). That means the vast majority of homes near Anthony C. Beilenson Park, along the Balboa Park corridor, and throughout the 91406 zip code fall well within both loan ceilings.
What does that actually look like for a buyer?
- FHA buyer at $950,000: With 3.5% down ($33,250), the loan amount of $916,750 clears the $1,249,125 limit with room to spare
- VA buyer at $950,000: With $0 down, the full purchase price is covered under the limit
- FHA buyer at $1,100,000: Even at the higher end of Lake Balboa pricing, 3.5% down ($38,500) produces a loan of $1,061,500, still comfortably under the ceiling
The takeaway for you as a seller: price is not the barrier. If your home is listed anywhere in the typical Lake Balboa range, FHA and VA buyers can afford it.
FHA loans between $832,750 and $1,249,125 in Los Angeles County are classified as “high-balance” FHA loans, per FHFA guidelines. These may carry slightly higher interest rates than standard FHA loans, but they still qualify buyers for properties throughout this neighborhood.
What VA and FHA Appraisals Check in Lake Balboa Homes
This is where many sellers hesitate, and where a little preparation goes a long way. VA and FHA appraisals are not just about value. They also evaluate basic health and safety conditions that conventional appraisals sometimes overlook.
Common items these appraisals flag include:
- Peeling or chipping paint, especially on pre-1978 homes (and Lake Balboa has plenty of mid-century housing stock)
- Broken windows or cracked glass
- Missing handrails on stairs or elevated decks
- Roof condition, including visible wear, missing shingles, or signs of active leaks
- Faulty electrical panels or exposed wiring
- Standing water or drainage issues around the foundation
What I tell my clients: fix these items before you list. Most of them are inexpensive. A handrail installation, a window replacement, a quick paint touch-up on the exterior trim. Spending a few hundred dollars on these repairs upfront prevents appraisal callbacks that can delay your closing by weeks.
With homes in Lake Balboa going pending in a median of 17 days as of mid-2026 (per local MLS data), you do not want to lose momentum because of a missing stair rail or peeling garage door paint. Speed matters in a market this tight.
Why VA and FHA Offers Can Be Just as Strong as Conventional Ones
This is the misconception I address most often when I sit down with Lake Balboa sellers. There’s a lingering belief that government-backed offers are somehow weaker, slower, or riskier than conventional financing. That belief costs sellers money.
Here is what the data actually shows:
Pre-qualification strength. FHA buyers need a minimum credit score of 580 and just 3.5% down. VA buyers can purchase with $0 down. But the underwriting standards are rigorous. By the time a VA or FHA buyer is pre-approved and writing an offer on your home near Victory Boulevard or Vanowen Street, their financials have been scrutinized thoroughly.
Closing timelines have narrowed. While FHA and VA loans historically took 40 to 45 days to close, experienced lenders in 2026 routinely bring these in at 30 to 35 days. The gap between conventional and government-backed closings is much smaller than it was five years ago.
Seller concessions are already standard practice. Across the San Fernando Valley, 52.9% of all closed sales involved seller concessions as of April 2026, per CRMLS data, with a median concession of $25,000. FHA allows sellers to contribute up to 6% of the purchase price toward buyer closing costs. VA allows up to 4% plus normal closing costs. Offering concessions to FHA and VA buyers is not unusual; it is the norm.
Having closed over 40 transactions across Northridge, Lake Balboa, Woodland Hills, and surrounding communities over my 6 years in real estate, I can tell you that the financing type on an offer matters far less than the buyer’s qualification level and their agent’s ability to manage the process.
Preparing Your Lake Balboa Home to Attract the Widest Buyer Pool
If you want to maximize your selling price, you need the largest possible pool of competing buyers. Here is how to position your property so VA, FHA, and conventional buyers all feel confident writing strong offers.
Address Safety and Condition Items First
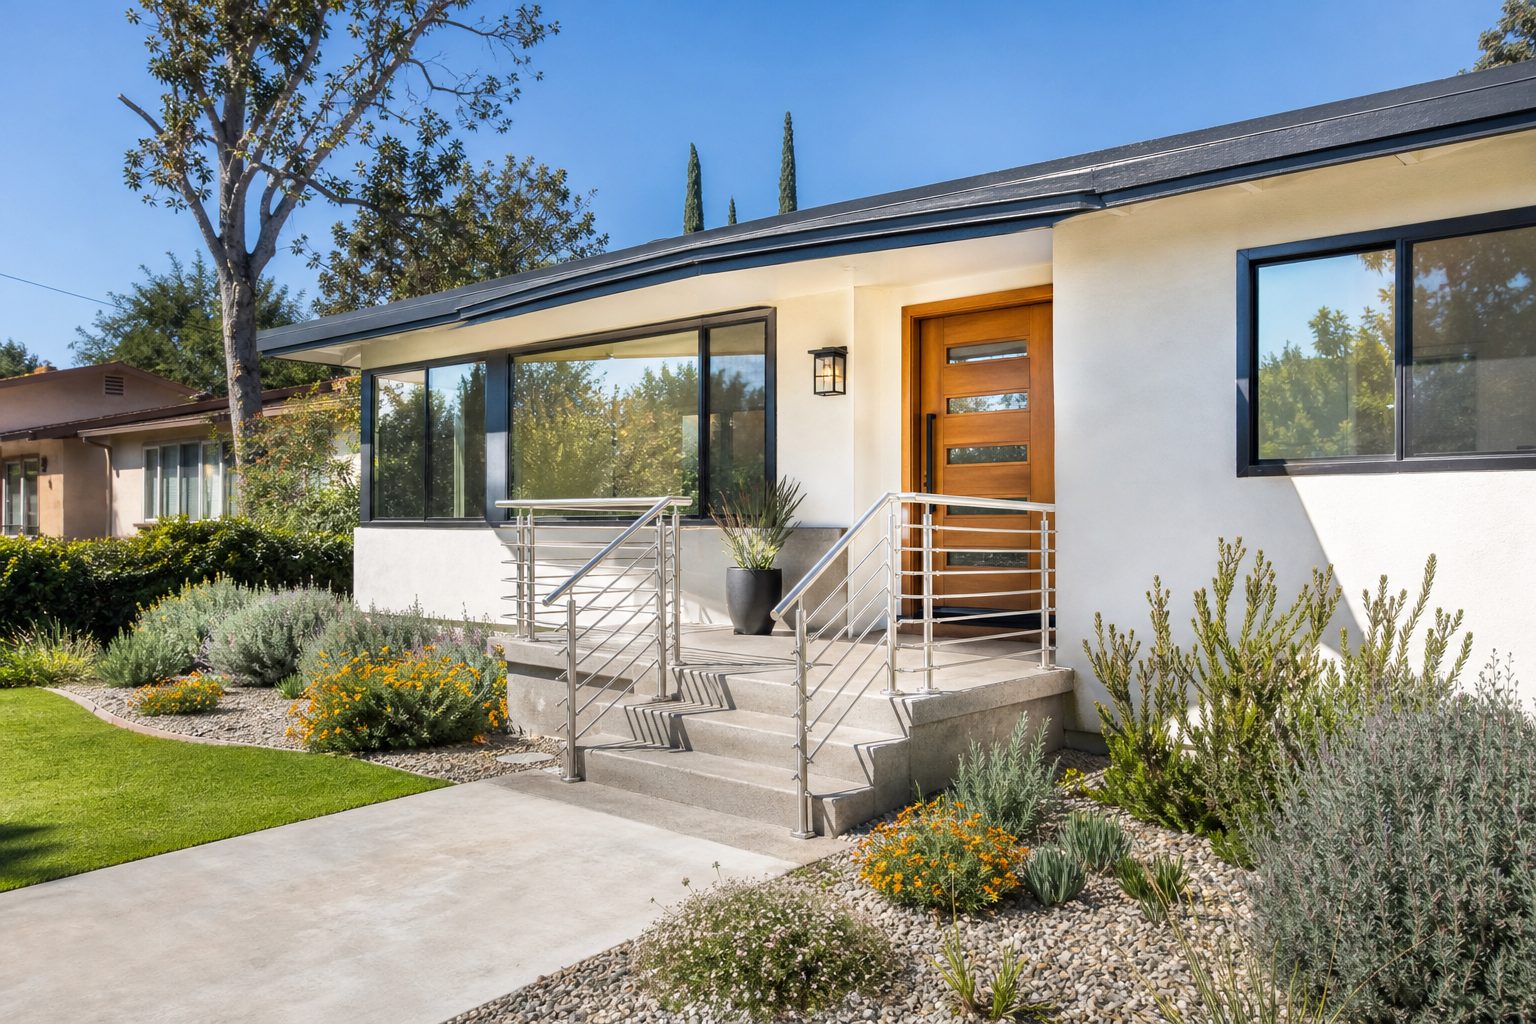
Walk your property with fresh eyes. Check every handrail, look at the roof from the street, examine window glass and frames, and look for peeling exterior paint. These are the items a VA or FHA appraiser will flag. Handling them before listing prevents delays and demonstrates pride of ownership to every buyer who walks through.
Price Correctly From Day One
Lake Balboa’s sold-to-list ratio of 104.6% as of mid-2026 (per local market data) tells you that accurately priced homes are generating competitive offers. Overpricing, however, pushes your listing past its peak momentum window. In a neighborhood with only 2.18 months of supply, the first two weeks on market are critical.
Consider Properties With ADU Potential
Properties with a permitted accessory dwelling unit, or clear space to add one, attract extra attention from buyers looking at rental income or multigenerational living. Multi-unit FHA limits in Los Angeles County reach $1,599,375 for a two-unit property in 2026, per FHFA data. If your Lake Balboa property has ADU potential, highlight it.
Do Not Discriminate by Loan Type
Under fair housing guidelines, you cannot reject an offer solely because it uses VA or FHA financing. Beyond the legal requirement, it is simply good strategy. A pre-approved VA buyer writing a clean offer at $920,000 is no less capable of closing than a conventional buyer at the same price. I know this firsthand because I was that VA buyer.
How Lake Balboa Compares to Neighboring San Fernando Valley Communities
Understanding where Lake Balboa sits in the broader Valley market helps you price appropriately and understand your buyer pool. As of April 2026, per CRMLS data:
- Encino: Median closed price of $2,440,000 (48 sales)
- Woodland Hills: Median closed price of $1,097,500 (70 sales)
- Northridge: Median closed price of $989,500 (42 sales)
- Lake Balboa: Median closed price of $899,500 (14 sales)
- Reseda: Median closed price of $845,500 (24 sales)
Lake Balboa offers strong value compared to neighboring Encino and Woodland Hills, with a price per square foot averaging around $600. That positioning makes it one of the most accessible single-family home neighborhoods in the western San Fernando Valley for VA and FHA buyers, while still delivering spacious lots and proximity to Beilenson Park.
Frequently Asked Questions
Can I reject an offer just because the buyer is using a VA or FHA loan?
No. Rejecting an offer solely based on financing type raises fair housing concerns. You can evaluate offers based on price, terms, contingencies, and buyer qualifications, but the loan program itself should not be your reason for declining. Evaluate every offer on its full merits.
What is the 2026 FHA loan limit in Los Angeles County?
The 2026 FHA loan limit for a single-family home in Los Angeles County is $1,249,125, according to Community First Mortgage data. This covers the vast majority of single-family homes in Lake Balboa, where typical prices range from $850,000 to $1.2 million.
What is the 2026 VA loan limit in Los Angeles County?
The 2026 VA loan limit is also $1,249,125 for a single-family property in Los Angeles County, per Homebuyer.com. VA buyers with full entitlement can purchase up to this amount with zero down payment.
Do VA and FHA appraisals require specific home repairs?
Yes. Both VA and FHA appraisals evaluate basic health, safety, and structural conditions. Common flagged items include peeling paint, broken windows, missing handrails, roof damage, faulty electrical systems, and drainage problems. Addressing these before listing prevents delays during escrow.
How long does a VA or FHA loan take to close compared to conventional financing?
FHA and VA loans historically took 40 to 45 days. In 2026, experienced lenders routinely close these in 30 to 35 days. The gap with conventional loans, which typically close in 25 to 30 days, is narrower than many sellers realize.
Are seller concessions common with VA and FHA buyers in the San Fernando Valley?
Yes. As of April 2026, 52.9% of all closed San Fernando Valley sales involved seller concessions, per CRMLS data, with a median concession of $25,000. FHA allows seller contributions up to 6% of the purchase price, and VA allows up to 4% plus standard closing costs.
How much does a VA buyer put down on a Lake Balboa home?
VA buyers can purchase with $0 down payment if they have full entitlement. On a $900,000 Lake Balboa home, that means the entire purchase price is financed, and the buyer brings only closing costs to the table.
How much does an FHA buyer put down on a Lake Balboa home?
FHA requires a minimum of 3.5% down with a credit score of 580 or higher. On a $950,000 home, that translates to approximately $33,250. California programs like CalHFA MyHome can cover that entire 3.5% as a deferred silent second, per mortgage-info.com, potentially bringing the buyer’s out-of-pocket down payment to $0.
Will accepting VA or FHA offers slow down my sale?
Not if the buyer is well-qualified and represented by a competent agent. Lake Balboa homes are going pending in a median of 17 days as of mid-2026. A pre-approved VA or FHA buyer with clean financials and an experienced lender can keep pace with that timeline.
Should I make repairs before listing to accommodate VA and FHA buyers?
Absolutely. The repairs required by VA and FHA appraisals, such as fixing handrails, replacing broken glass, and addressing peeling paint, are generally inexpensive and benefit all buyers, not just government-backed ones. These improvements also enhance your curb appeal and listing presentation.
The Bottom Line
Selling your Lake Balboa home in 2026 means positioning it for the broadest possible buyer pool. With the VA and FHA loan limits both set at $1,249,125 in Los Angeles County, and Lake Balboa’s typical single-family home prices running in the $850,000 to $1 million range, there is no financial reason to exclude government-backed buyers from your strategy.
Fix the small safety and condition items before you list. Price accurately from day one. Evaluate every offer on its actual terms, not its loan type. Learn more about homebuying assistance programs to understand the full range of options available to your buyers. Rated 5.0 out of 5 stars by 31 past clients and ranked number 8 among over 150 agents at Park Regency Realty in 2025, I bring the discipline I learned as a U.S. Army Sergeant to every listing I represent across Lake Balboa, Northridge, and the western San Fernando Valley. If you are considering selling and want to make sure your home is positioned to attract every qualified buyer, call Seann Brown at 818-960-3501 or visit seannhomes.com.

Leave a Reply