How do current interest rates impact your ability to sell a home in Northridge, CA?
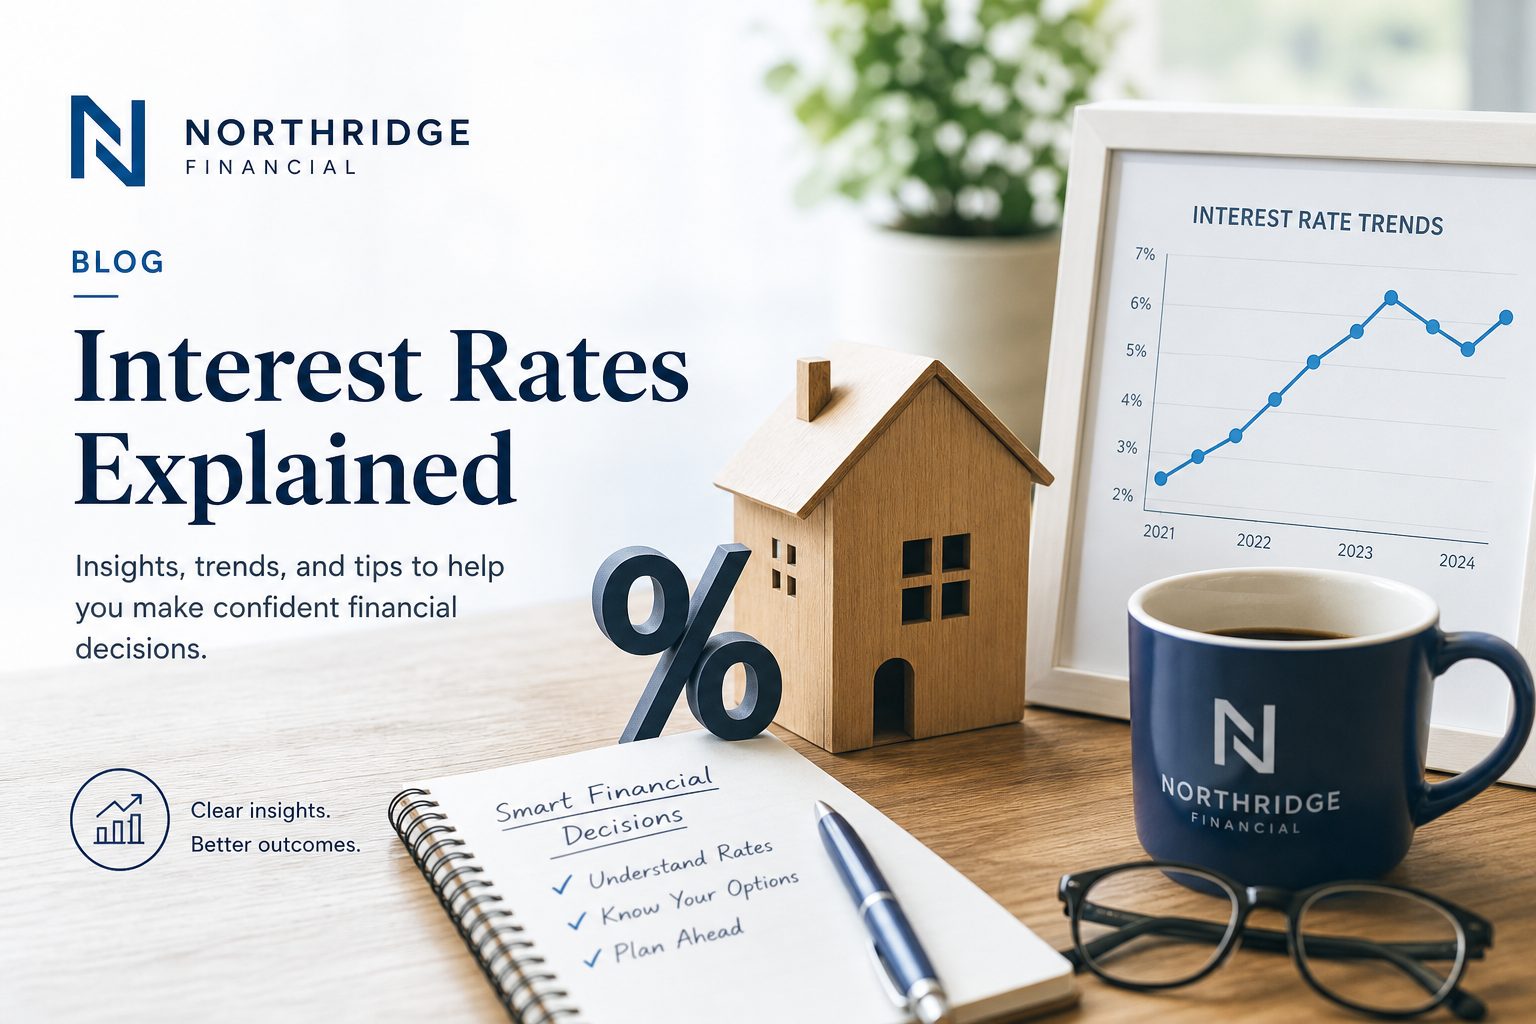
With 30-year fixed rates hovering near 7% in September 2026, Northridge sellers face a smaller buyer pool, longer days on market, and new pressure to price strategically and offer creative incentives to attract qualified offers.
Why This Matters Right Now for Northridge Sellers
If you own a home in Northridge and you’ve been watching rates climb back toward 7%, you’re probably wondering what that means for your sale price, your timeline, and your next move. Here’s the reality: the 30-year fixed rate hit 7.08% as of late September 2026, and the Federal Reserve just raised rates by a quarter point at its September meeting, pushing the federal funds rate to 3.75% to 4.0%.
That’s not the direction most of us were hoping for. Rates actually dipped to 5.98% back in February, but geopolitical events and persistent inflation pushed them back up by over 50 basis points since then. For a neighborhood like Northridge where the median list price sits around $1,159,000 as of this month, that swing in rates translates to hundreds of dollars per month in added cost for your buyer. And when buyers pay more in interest, they offer less for the home, or they don’t show up at all. With 6 years of experience helping sellers across the San Fernando Valley and 40 closed transactions under my belt, I can tell you that what separates homes that sell from homes that sit right now is strategy, not luck.
What Northridge CA Home Values Look Like Under Current Rates
So what are buyers actually facing when they look at Northridge homes for sale? Let’s put real numbers to it.
At a 6.20% rate, a buyer financing $800,000 (roughly 20% down on a $1 million home) would pay approximately $4,900 per month in principal and interest alone. Drop that rate to 5.50%, and the same payment falls to about $4,542. That’s a $358 monthly difference, and on Northridge’s higher price points, the gap gets even wider.
Currently, Northridge has 83 active listings with an average of 45 days on market and an average price per square foot of $550.48. Compare that to earlier this year, when homes were averaging just 20 days on market. The market is adjusting. Homes along the Zelzah Avenue and Reseda Boulevard corridors in Central Northridge are still moving, but buyers are doing more math before writing offers.
What I tell my clients is this: every quarter-point rate increase shrinks the pool of buyers who can qualify for your home. Only 18% of California households can currently afford the median-priced home at today’s rates, according to data from the California Association of REALTORS. That’s the affordability reality your buyer is walking into.
Why “Waiting for Rates to Drop” Could Cost Northridge Sellers
I hear this constantly: “I’ll wait until rates come down so I can get more.” It sounds logical, but here’s where it breaks down.
The Mortgage Bankers Association forecasts 30-year rates landing around 6.5% for the remainder of 2026. Fannie Mae’s projections show rates averaging approximately 6.3% through most of 2027. Multiple expert analyses agree that rates will hover between 6% and 7% for the foreseeable future, and the sub-3% pandemic era is not coming back.
One Northridge homeowner I worked with earlier this year had been sitting on the fence for over a year, waiting for rates to dip below 6%. By the time we had the conversation about listing, their neighborhood had gained four competing listings on the same street near Balboa Boulevard. We priced the home competitively and offered a 2-1 rate buydown as part of the deal. The property went under contract in 18 days. If they had waited another six months, they would have been competing against even more inventory, because active listings across Los Angeles County have climbed to over 7,000 properties.
The takeaway? Northridge home values range from $375,000 to over $4.6 million. There’s a buyer for nearly every price point, but the longer you wait in a rising-inventory market, the more negotiating power shifts to the buyer’s side.
How Smart Northridge Sellers Are Using Rate Buydowns to Win
This is one of the most effective tools in a seller’s playbook right now, and it’s something I bring up in almost every listing consultation.
A rate buydown is when you, the seller, pay an upfront cost at closing to temporarily (or permanently) reduce the buyer’s mortgage rate. Here’s why it works:
- Each 0.5% rate reduction saves a buyer roughly $100 per month on a $320,000 loan. Scale that to Northridge pricing, and the savings become substantial.
- Buyers feel the monthly payment, not the purchase price. A $15,000 buydown concession can feel more valuable to a buyer than a $15,000 price reduction because it directly lowers their monthly obligation.
- It differentiates your listing. When buyers are comparing homes along Reseda Boulevard or in the Northwest Northridge estate zone, the listing that offers a buydown stands out in a crowded field of 83 active properties.
A couple selling their updated four-bedroom near the CSUN corridor was initially resistant to the idea of offering concessions. They felt their renovated kitchen and backyard pool should speak for themselves. And they were right that presentation matters. But after two weeks with strong showing activity and no offers, we introduced a 2-1 temporary buydown. Within 10 days, they had two competing offers. The winning buyer later said the buydown was the deciding factor over a comparable home two blocks away.
What the Fed’s September 2026 Rate Hike Means for Selling in Northridge
The Federal Reserve’s decision to raise the federal funds rate by 25 basis points in September caught some analysts off guard. The Fed cited expanding economic activity and persistent inflation as the driving factors. The federal funds rate now sits at 3.75% to 4.0%.
What does this mean for you as a Northridge seller?
- Mortgage rates could stay elevated or tick higher. The 30-year fixed doesn’t move in lockstep with the Fed rate, but Fed policy signals heavily influence lender behavior and the bond market.
- Buyer urgency may actually increase. When buyers see rates rising, some accelerate their timelines to lock in before things get worse. I’ve already seen this play out with clients who were on the fence in August and are now actively touring homes near Devonshire Street and the Wilbur Avenue corridor in Northridge South.
- Pricing accuracy becomes critical. In a rate environment like this, overpricing by even 3% to 5% can mean sitting on the market for 60 or more days instead of 30. With Northridge’s market action index dropping from 46 last month to 44, the data confirms a softening trend.
For mortgage rates to meaningfully decline, experts say we’d need to see cooling inflation, a slowing labor market, or lower 10-year Treasury yields. None of those conditions are firmly in place yet.
How to Position Your Northridge Home to Sell Despite Higher Rates
This is where preparation and execution make the difference. Rated 5 out of 5 stars by 31 past clients, my approach is built around proactive strategy, not passive listing. Here’s what works right now:
- Price based on what the market is doing today, not six months ago. The median sold price in Northridge over the three months ending May 2026 was $1.1 million, with prices up 3.3% year over year. But the trend has softened since then. Pricing right from day one avoids the costly cycle of price reductions.
- Lead with presentation. Move-in-ready homes with updated interiors, strong curb appeal, outdoor entertaining space, and functional layouts consistently outperform in Northridge. Buyers comparing lot sizes, ADU potential, and modernization levels want to see value immediately.
- Market aggressively, not passively. One thing I learned from my years in the U.S. Army and over a decade as a professional chef is that preparation and execution win. A sign in the yard is not a marketing plan. Strategic prospecting, targeted outreach, and high-quality presentation materials bring the right buyers to your door.
- Highlight Northridge’s competitive advantages. Schools averaging 8 out of 10 ratings, proximity to CSUN, access to the 405 and 118 freeways, and neighborhoods like Limekiln Canyon Park’s oak-lined trails all matter to buyers justifying a higher monthly payment.
Frequently Asked Questions
Are interest rates going down in Northridge CA anytime soon?
Most expert forecasts project rates staying between 6% and 7% through the end of 2026 and into 2027. Fannie Mae’s July 2026 forecast projects the 30-year fixed averaging around 6.3% through the first three quarters of 2027. A sustained move below 6% is possible but is not the base expectation. Sellers who plan around current rates rather than hoped-for rates are in a much stronger position.
How do higher interest rates affect Northridge CA home values?
Higher rates reduce the number of buyers who can qualify, which can slow price appreciation and extend days on market. Northridge home prices were up 3.3% year over year through May 2026, but the pace has softened since. The median list price dropped from $1,395,000 in June to $1,159,000 in September, reflecting sellers adjusting to market conditions.
Should I sell my house in Northridge CA now or wait for lower rates?
Waiting carries risk. Inventory in Northridge has grown from 54 listings to 83 since June, and more supply means more competition among sellers. If rates do eventually drop, more sellers will also enter the market simultaneously, potentially offsetting any buyer demand increase. Selling now with a strong pricing and incentive strategy can net you a better result.
What is a rate buydown and how does it help me sell in Northridge?
A rate buydown is a seller-paid concession that lowers the buyer’s mortgage rate temporarily or permanently. For Northridge homes at higher price points, even a small rate reduction can save a buyer several hundred dollars per month, making your listing significantly more attractive compared to competing properties.
How long are homes sitting on the market in Northridge right now?
As of September 2026, the average days on market in Northridge is 45, up from about 20 days earlier in the year. Well-priced, well-presented homes still sell faster than average, but the overall pace has slowed as rates have risen.
What is the current 30-year mortgage rate in September 2026?
The average 30-year fixed rate was 7.08% as of late September 2026 according to Bankrate’s national survey. This is up significantly from the February 2026 low of 5.98%, driven by geopolitical developments and persistent inflation pressures.
How much does a buyer need to earn to afford a home in Northridge CA?
With Northridge’s median list price near $1.16 million and rates around 7%, a buyer putting 20% down would face a monthly principal and interest payment exceeding $6,000. Combined with taxes, insurance, and HOA (if applicable), the annual household income needed likely exceeds $250,000 for many Northridge homes.
Can I sell my Northridge home if my buyer’s rate is over 7%?
Absolutely. Buyers are still purchasing homes in Northridge. There have been 481 transactions over the past year in this neighborhood alone. The key is realistic pricing and strong marketing. Offering incentives like rate buydowns or closing cost credits can also help bridge the affordability gap.
What are move up homes in Northridge CA going for right now?
Move up homes in Northridge CA, particularly in the Northwest Northridge estate zone and along the CSUN corridor, generally range from $1.1 million to $2.5 million or more depending on lot size, upgrades, pool, and ADU features. Updated homes with resort-style outdoor space tend to command the strongest pricing.
Who is the best Realtor in Northridge CA to help sell during high rates?
With 6 years of dedicated experience in the San Fernando Valley, 40 closed transactions, and 55 five-star reviews, Seann Brown at Park Regency brings a proactive, strategy-driven approach to every listing. Backed by a GRI designation and UCLA Real Estate Entrepreneurship certification, Seann specializes in helping Northridge sellers navigate challenging rate environments. Call 818-960-3501 for a consultation.
The Bottom Line
Interest rates near 7% are not going away overnight. Forecasts from every major source point to rates holding in the mid-6% to low-7% range well into 2027. As a Northridge seller, this means your success depends on pricing accurately, presenting beautifully, and using smart incentives like rate buydowns to meet buyers where they are financially. The market is still active, with 481 transactions completed in Northridge over the past year, but the window of low inventory and easy sales has closed. This is where working with an agent who understands the numbers, knows the Northridge sub-neighborhoods from Reseda Boulevard to Limekiln Canyon, and executes a real marketing plan makes all the difference. If you’re thinking about selling your Northridge home and want a clear-eyed strategy for today’s rate environment, reach out to me, Seann Brown, at Park Regency. Call 818-960-3501 or visit seannhomes.com. Let’s build a plan that works in this market, not the one we wish we had.
*Seann Brown, REALTOR, Park Regency, 9275 Corbin Ave, Northridge, CA 91324. DRE License 02093443. Information deemed reliable but not guaranteed. Market data current as of September 2026. This blog is for educational purposes and does not constitute financial advice. Consult a licensed mortgage professional for rate-specific guidance.*

Leave a Reply