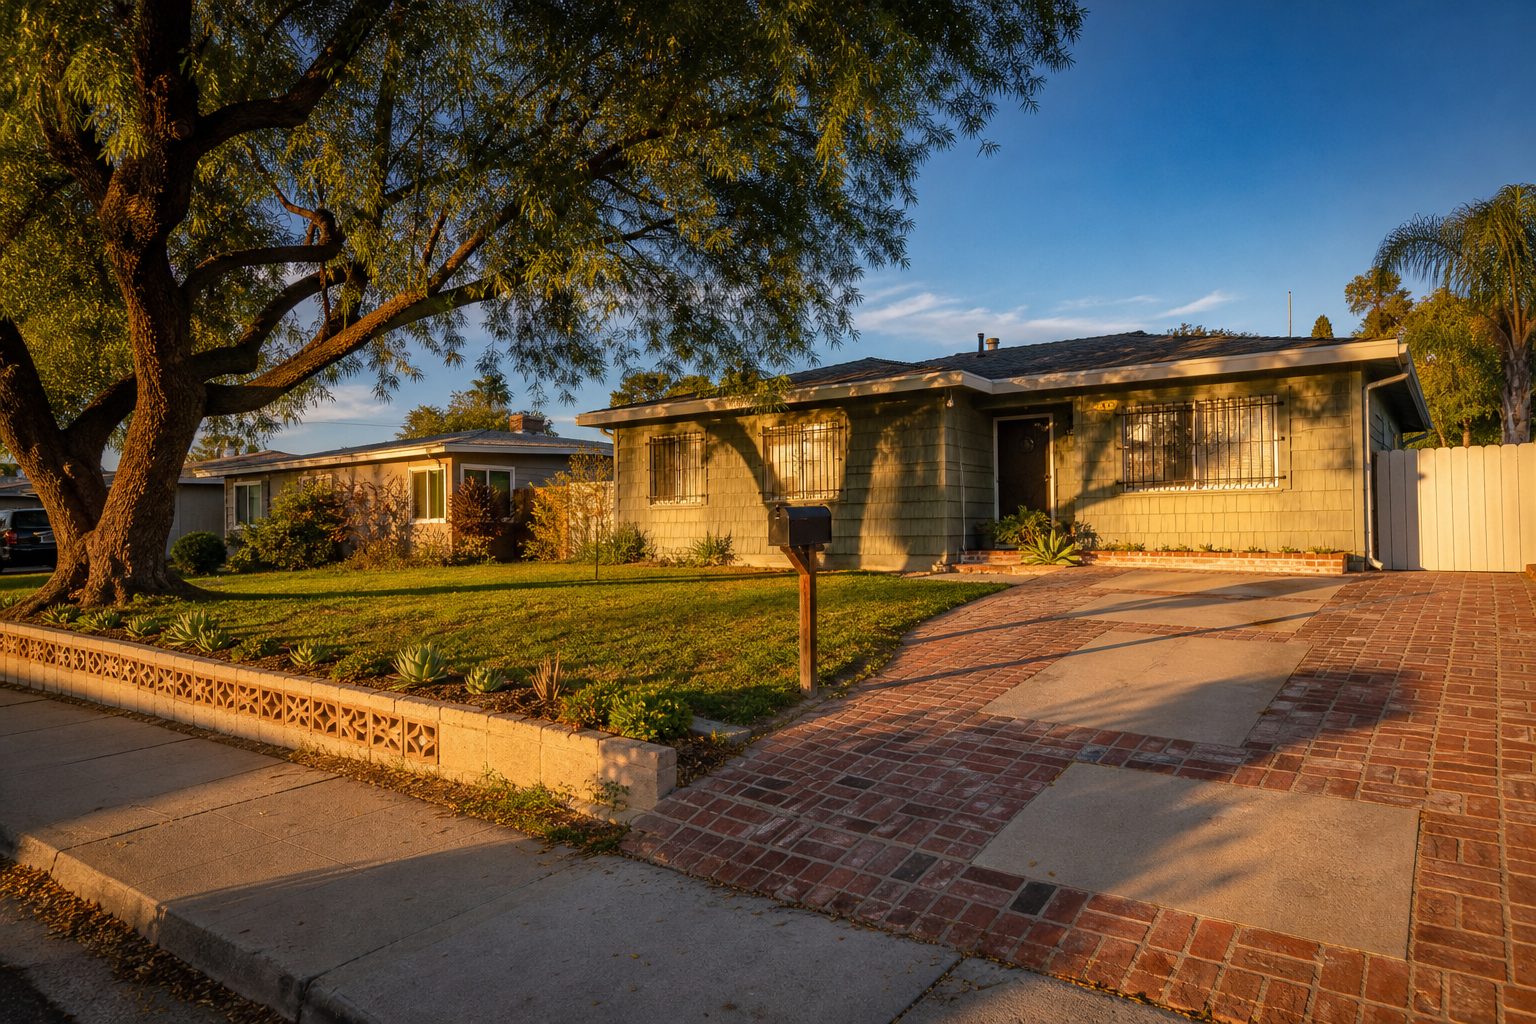
If you own your 1950s three bedroom home free and clear in the blocks between Saticoy St and Roscoe Blvd, east of Woodley Ave, should you carry the loan for a buyer who cannot qualify at today’s mortgage rates?
Seller financing can work for a free and clear Lake Balboa homeowner who prioritizes steady monthly income over a lump sum, but only with a substantial down payment, careful buyer screening, proper legal documents, professional loan servicing, and guidance from a real estate attorney and CPA.
Why Lake Balboa 91406 Seller Financing Matters Right Now
The math has changed for buyers trying to purchase in your neighborhood. According to Freddie Mac’s Primary Mortgage Market Survey, the 30 year fixed mortgage rate was 7.24% on October 29, 2026, down from 7.32% the week before but up from 6.17% a year earlier. The 15 year fixed was 6.60%.
What does that mean for you in a paid off home between Saticoy and Roscoe? Some buyers with solid income and savings cannot get approved for the loan they need at these rates. Because you have no mortgage, you are in a position to offer terms a bank will not.
For ZIP code 91406 over the three months ending September 2026, the median sale price was $891,238, down just 0.6% year over year, per Redfin. Homes sold at 99.4% of list on average, with a median of 42 days on market, down from 50 a year earlier, and 37.0% sold above list. Redfin calls 91406 somewhat competitive, and 31.9% of homes had a price drop. Seller financing can widen your pool of buyers.
How a Seller Carryback Actually Works in Lake Balboa
So how does this actually function? You sell your home at market value. The buyer makes a down payment. Instead of a bank funding the remaining balance, you carry the note. The buyer signs a promissory note to you, secured by a deed of trust recorded against the property, and because you own the home free and clear, your deed of trust would be the first loan recorded against it.
Every month, the buyer sends a payment covering principal and interest, just like a mortgage. You collect that payment as income. If the buyer stops paying, the deed of trust lets you foreclose through the same California trustee sale process a bank uses, and you can take the property back if no one outbids you.
Because you own the home outright, there is no bank loan ahead of you. Property taxes still take priority over any deed of trust, which is one reason to require an impound account.
Seller financing is not a favor you do for a buyer. It is a financial tool, used with proper legal protections, to reach a specific goal. In your case, that goal is steady monthly income.
What Your Monthly Income Could Look Like in Lake Balboa 91406
Your income depends on the price your home commands, so the starting point is a pricing analysis based on recent closed sales near you. For context, the 91406 median sale price was $891,238 in the three months ending September 2026, per Redfin.
If your home sells at market value, the monthly payment on the note could be meaningful income. The exact amount depends on the sale price, down payment size, interest rate, and amortization term you negotiate.
Key Terms You Control
- Down payment size. A larger down payment gives the buyer more to lose and lowers your risk. It also provides you with an immediate lump sum for reserves or expenses.
- Interest rate. You and the buyer negotiate the rate. Compare it with the current 7.24% average, and ask your CPA about the IRS minimum interest rules (the applicable federal rate).
- Term and balloon. Some notes use a 30 year payment schedule with a balloon payment due after a few years, meaning the buyer must refinance or pay off the balance by then. Federal rules limit balloons for some sellers, as explained below.
I have been licensed since 2020 and have closed 40 transactions, and my MLS listings average 17 days on market at 101% of list price. For this decision I build a net sheet comparing a conventional sale with a carryback scenario, so you see the full picture before deciding.
California Legal Protections and Disclosure Requirements for Lake Balboa Sellers
This is not something you structure on a handshake. California law has specific requirements for seller financing on one to four unit residential properties.
This is not legal, tax, or lending advice. A real estate attorney and CPA should review any terms before you proceed.
California Civil Code Section 2956
Under Civil Code sections 2956 through 2967, when a seller extends credit on the sale of a dwelling of one to four units and an arranger of credit is involved (a real estate agent usually counts), a written seller financing disclosure must be given to both buyer and seller. It covers the terms of the note, the buyer’s credit and employment information, and warnings about balloon payments and other risks. The California Association of REALTORS® Seller Financing Addendum and Disclosure (SFA) is the form agents commonly use.
Balloon Payment Notice Rules
If your note has a balloon and a term over one year, Civil Code section 2966 (or section 2924i when no arranger of credit is involved) requires you to mail a written notice 90 to 150 days before the balloon is due. If you skip it, the debt is not wiped out, but the due date moves to at least 90 days after you send the notice.
Anti Deficiency Protection
Here is something many sellers do not realize: Code of Civil Procedure section 580b bars a deficiency judgment on a deed of trust given to the seller to secure the balance of the purchase price. That means if the buyer defaults and the home has lost value, you likely cannot pursue them personally for the shortfall. This is exactly why a substantial down payment is so critical.
Federal Loan Originator Rules
The Dodd Frank Act loan originator rules in Regulation Z (12 CFR 1026.36) exclude some sellers. A person, estate, or trust that seller finances only one property in a 12 month period is excluded if the loan has no negative amortization and either a fixed rate or a rate that stays fixed for at least five years and then can change only within reasonable limits; a balloon is allowed. A seller who finances up to three properties in 12 months must also make the loan fully amortizing, with no balloon, and decide in good faith that the buyer can repay. Other Truth in Lending rules may apply depending on the structure, so have your attorney review it. The Consumer Financial Protection Bureau publishes guidance on mortgage financing options and when seller financing triggers these requirements.
IRS Installment Sale Reporting
Under IRS Topic 705, if you sell on an installment basis, you generally report the gain on Form 6252 as you receive principal payments, rather than all in the year of sale. The interest you receive is taxed as ordinary income, and a note with too little interest can be recharacterized using the applicable federal rate. Your CPA should model both scenarios, including any home sale exclusion you may qualify for.
The Real Risks of Carrying a Note in Lake Balboa
Here is what can go wrong, and how to protect yourself.
Buyer Default
A buyer who cannot qualify for conventional financing may carry higher credit risk. You need to screen this buyer’s credit history, income documentation, and employment stability carefully, just as a bank would.
Foreclosure Timeline
If the buyer stops paying, California nonjudicial foreclosure takes at least three months and 20 days from the Notice of Default under Civil Code sections 2924 and 2924f, and the buyer can reinstate until five business days before the sale. During that time, you are not receiving income and may be dealing with a property that is not being maintained.
Property Deterioration
Once the buyer moves in, they control the property. If they neglect maintenance, the value of your collateral declines. Requiring hazard insurance with you named as loss payee, and including an escrow impound for property taxes and insurance, protects you.
Practical Safeguards
- Use a loan servicing company to collect payments, handle the impound account, and provide tax forms.
- Have a real estate attorney draft the promissory note and deed of trust, not just a standard form.
- Get a lender’s title insurance policy for your deed of trust.
- Address the note in your estate plan. If something happens to you, the note becomes an income producing asset your heirs can inherit or sell to a note investor.
A past client wrote this on Google: “Seann is an excellent agent. Very professional and a market expert. I strongly recommend his services if you are looking to buy or sell.”
How I Help Lake Balboa 91406 Homeowners Evaluate This Decision
Every seller I work with gets my 18 point 4 phase listing plan in writing. For a potential seller financing scenario, I start with a seller net sheet that compares the conventional sale outcome against a carryback structure, so you can see both paths side by side before committing to anything.
I price at market value using current comparable sales near you. At 9419 Haskell Ave in North Hills, a listing that sat a year with another agent drew 5 offers and sold for $886,000 on an $875,000 list price in June 2026 after I took it over. At 22031 Gilmore St in Woodland Hills, the home drew 3 offers and sold for $1,200,000 on a $1,149,999 list in 9 days in July 2025. The strategy is the same whether you go conventional or carryback: price right first, then evaluate terms.
I have over 55 five star reviews across Google, Zillow and Yelp with a 5.0 average rating, and I ranked #8 of more than 150 agents at Park Regency Realty in 2025. I am a U.S. Army veteran who served in Iraq and Kosovo, and I cooked professionally as a Le Cordon Bleu trained chef for 10 years. Details matter in seller financing.
Frequently Asked Questions About Seller Financing in Lake Balboa
What is the biggest advantage of seller financing for a Lake Balboa homeowner who owns free and clear?
With no existing mortgage, your deed of trust would be the first loan on the home, with no bank ahead of you. You also create a monthly income stream, and under IRS Topic 705 you can generally spread the taxable gain over the years you receive payments.
What interest rate can I charge on a seller financed sale in California?
The rate is negotiated between you and the buyer. Ask your attorney how California usury law applies to your terms; a true seller carryback is often treated differently from a loan. For comparison, Freddie Mac reported a 7.24% average 30 year rate on October 29, 2026, and your CPA can confirm the IRS minimum interest rate.
What happens if the buyer stops paying?
You can start foreclosure under the deed of trust. California nonjudicial foreclosure takes at least three months and 20 days from the recorded Notice of Default, and the buyer can reinstate until five business days before the sale. If no one outbids you at the sale, you can take the property back. Code of Civil Procedure section 580b generally prevents you from pursuing the buyer personally for any shortfall.
Do I need a real estate attorney for a seller financed sale in Lake Balboa?
Yes. The promissory note, deed of trust, and any disclosures required under California Civil Code sections 2956 through 2967 are legal documents with real consequences. A licensed real estate attorney should draft and review all documents. This is not something you handle with standard forms alone.
How does seller financing affect my taxes?
Under IRS Topic 705, an installment sale generally lets you report the gain as you receive payments rather than all at once, using Form 6252. Interest you receive is ordinary income. A CPA should model both conventional and installment scenarios for your specific situation.
What is a balloon payment, and should my note include one?
A balloon payment is a lump sum due at a set date. It limits how long your money is tied up, but the buyer must refinance or pay it off, and federal rules do not allow a balloon if you finance more than one property in 12 months. Civil Code section 2966 or 2924i requires a written notice 90 to 150 days before the balloon is due, or the due date is pushed back.
How do I screen a buyer who cannot qualify for a conventional mortgage?
Review their credit report, income documentation, employment history, and bank statements, just as a lender would. The fact that they cannot qualify at 7.24% does not automatically mean they are a bad credit risk; some buyers have strong income but are blocked by debt to income ratio thresholds at current rates. Your attorney and a loan servicing company can help you set screening standards.
Should I require hazard insurance from the buyer?
Yes. You should require the buyer to maintain hazard insurance with you named as loss payee throughout the life of the note. Including an escrow impound for property taxes and insurance, just as a bank would require, protects the value of your collateral.
Can I sell the note later if I need a lump sum?
Yes. A secondary market exists for performing real estate notes. Note investors typically purchase at a discount from the remaining balance. Having a well documented note with a strong payment history and proper title insurance makes the note more marketable if your circumstances change.
What happens to the note if I pass away?
The promissory note becomes an asset of your estate. Your heirs can continue collecting payments, or they can sell the note to an investor. It is important to address the note specifically in your trust or will so there is no confusion about who manages it.
The Bottom Line for Lake Balboa 91406 Homeowners
If you own a paid off 1950s three bedroom home in the blocks between Saticoy St and Roscoe Blvd, east of Woodley Ave, seller financing can turn your equity into monthly income at a time when rates above 7% are keeping some buyers from qualifying. But it only works with proper legal structure, professional loan servicing, buyer screening, and guidance from a real estate attorney and CPA.
You do not have to figure this out alone. I am Seann Brown, a listing focused REALTOR® with Park Regency Realty at 9275 Corbin Ave in Northridge, and I completed GRI and UCLA real estate training. I build every seller a side by side net sheet comparing conventional and carryback outcomes before any decisions are made. Call or text me at 818.960.3501, and let’s look at the numbers together for your specific home.
